Delaware Statutory Trust Structure and Investor Rights
DST investment surged 49% in 2025, driven by investors racing against 1031 exchange deadlines.
Delaware Statutory Trust Structure and Investor Rights.
Why DST investment volume has surged
Delaware Statutory Trusts moved a lot of money in 2025, with sponsors raising $8.41 billion, up roughly 49% over the prior year DST Investment Advisors JLL Income Property Trust. The same research firm expects 2026 to be somewhere between $10 billion and $11 billion in DST sales, and by May of this year, DST inventory had hit a record: about $3.9 billion in available equity spread across roughly 100 offerings DST Investment Advisors JLL Income Property Trust JLL Income Property Trust.
Some of that growth traces back to plain timing pressure. Investors doing a 1031 exchange face 45/180-day pressure, and a pre-packaged DST solves the "no replacement in time" problem that causes a meaningful share of the 10%–20% of commercial deals involving a 1031 exchange to collapse DST Investment Advisors eisneramper.com. A meaningful share of those deals fall apart simply because no replacement property was ready in time, and a pre-packaged DST, already built, already titled, already leased, solves that problem in a way raw property shopping cannot DST Investment Advisors eisneramper.com.
None of that growth is a reason to relax. If anything, it cuts the other way: more capital flowing into DSTs means more investors signing onto a legal structure whose terms they may not have fully worked through before wiring exchange proceeds. The same structural features that make DSTs attractive, passive management, institutional-grade assets, quick closing, are inseparable from the rights investors give up. Understanding what those rights are, and why the structure requires giving them up, is the whole subject of what follows.
The DST legal entity structure and how it holds real estate
That single filing creates a legal entity that can hold title to real property in its own name.
And it does hold the whole thing. The trust owns 100% of the interest in the underlying real estate, not a slice of it, and investors don't own the property directly at all DST Investment Advisors. What they own is a beneficial interest in the trust that owns the property DST Investment Advisors. The IRS, for its part, treats a properly structured DST as a grantor trust. Investors are treated as the direct owners of the real estate for tax purposes even though legal title sits with the trust. In practice that means each investor gets a grantor trust letter at tax time and reports a pro-rata share of income and expense on a personal return, a K-1 the way a partnership investor would.
The ownership chain runs in one direction. A sponsor acquires the property first, then places it into the trust, then owns all of the trust's beneficial interests itself, and only then sells those interests off to individual investors as replacement property for their 1031 exchanges. There's no cap on how many investors can buy in, a real point of contrast with a tenant-in-common structure, where IRS guidance caps ownership at 35 investors. And because these interests are unregistered securities, they're sold via SEC-exempt private placement under Regulation D. A DST is a trust formed and governed under Delaware law, created by filing a Certificate of Trust with the Delaware Division of Corporations.
How beneficial interest ownership differs from direct property ownership
Owning a rental property outright means making the calls yourself. You set the lease terms, you decide whether to refinance, you choose when to renovate, and you choose when to sell. A DST beneficial interest holder gets a percentage of the income, the depreciation, and the eventual sale proceeds, but none of the levers that go with direct ownership. The trustee, usually the sponsoring company, runs every operational decision: leasing, maintenance, tenant relations, disposition, all of it. There is no shareholder vote on whether to replace the roof or renegotiate a lease. The investor's role, once the money is in, is to receive distributions and file taxes.
Debt works differently here than most investors expect. If the DST is leveraged with non-recourse debt, each beneficiary assumes a pro-rata share of that debt, relevant for 1031 exchange debt-matching requirements, but has no personal exposure beyond invested equity. The debt is non-recourse at the beneficiary level. Exposure stops at the invested equity.
Liquidity is where the trade-off bites hardest. There is no secondary market for DST interests. An investor who wants out finds that exit requires a liquidation event, a property sale, or, in some structures, a conversion to UPREIT; investors cannot independently sell their interest the way they could sell a rental property. Selling a fractional interest independently, the way you'd list a rental property, isn't an option. This isn't a design flaw or an oversight on the sponsor's part. This illiquidity is not incidental, it is structurally baked in by the same IRS rules that make DSTs eligible for 1031 exchange treatment. Loosening the restrictions on transfer and reinvestment risks the trust losing its qualifying status.
The two structures often get lumped together, and the alternative involves investor first completing a 1031 exchange into a DST, then, after a holding period, contributing their DST interest to a REIT's operating partnership in exchange for operating partnership (OP) units. In a TIC, co-owners have to act unanimously on operational matters, but each owner can transfer their own slice of the interest independently. A DST flips that: the trustee acts alone on operations, and transfer is heavily restricted. In a DST the trustee acts alone and transfers are severely restricted, making the DST more passive, more rigid, and typically used for larger assets, unlike a TIC where co-owners must act unanimously.
The seven rules from Revenue Ruling 2004-86 that define the outer boundary of what a DST trustee and investors can do
Everything about a DST's rigidity traces back to a single piece of IRS guidance: Revenue Ruling 2004-86. That ruling is what lets a DST beneficial interest count as like-kind replacement property for a 1031 exchange, and in exchange for that treatment, it locks the trust into a narrow set of behaviors DST Investment Advisors eisneramper.com. Stepping outside those behaviors risks reclassification as a "business trust," which would knock it out of 1031 eligibility altogether.
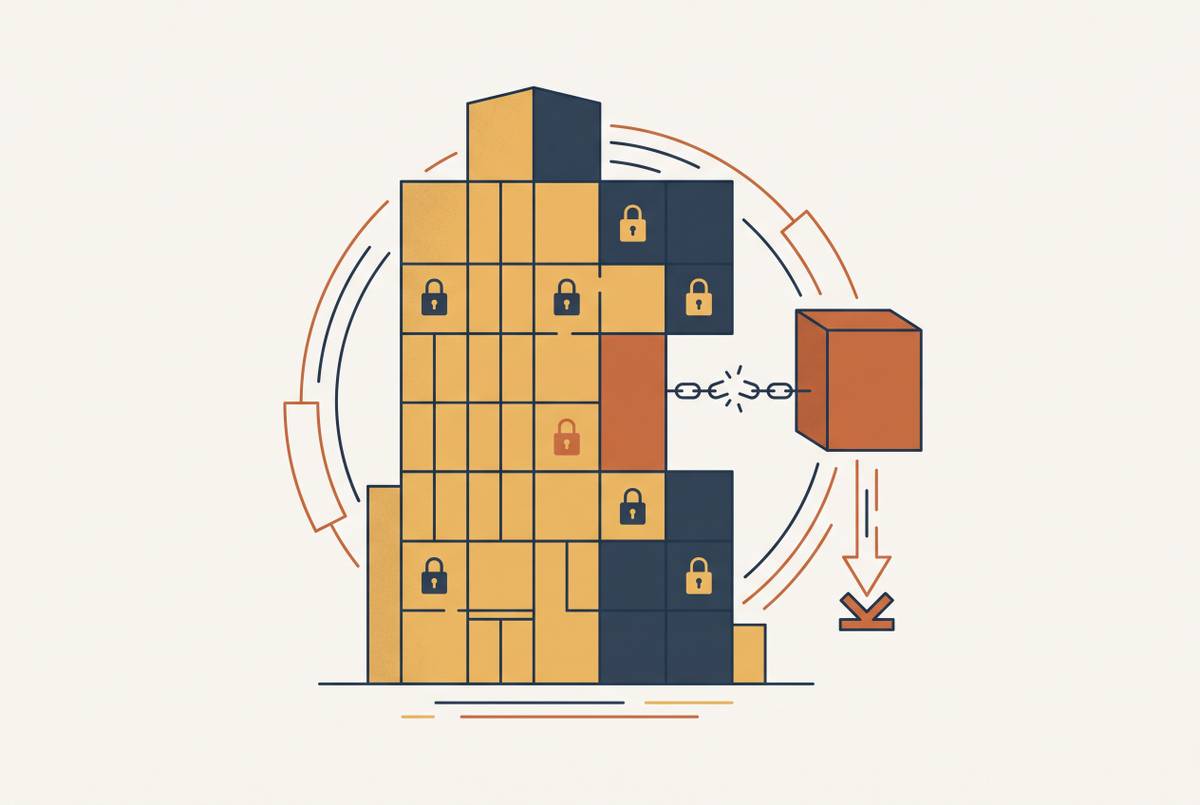
The restrictions are specific and unforgiving. Once an offering closes, no additional capital can go into the trust, from existing investors or new ones. The trustee can't refinance the existing loan or place new debt on the property, the financing is frozen at whatever terms existed when the offering closed. Leases can't be renegotiated and new leases can't be signed, with one narrow carve-out for a tenant that's gone insolvent or into bankruptcy. Nearly all cash has to go out to investors on at least a quarterly basis, reserves aside, so the trust can't sit on cash and wait for a better use of it. Whatever reserves the trust does hold can only sit in short-term instruments or government securities, no speculative redeployment. Capital spending is limited to normal repair and maintenance, non-structural upgrades, or bringing the property into legal compliance, nothing that amounts to repositioning the asset. And when the property eventually sells, the proceeds go out to investors rather than getting reinvested into something new inside the same trust.
None of this is negotiable, and none of it bends for a good reason. A trustee who violates any one of these restrictions can trigger immediate taxation of investor income, collapsing the deferral the entire exchange was built around. That means a DST trustee, unlike a direct owner or even a REIT asset manager, can't respond to a market opportunity in real time. A tenant offering better terms, a chance to refinance into a lower rate, a sudden opening to add a wing to a warehouse, none of that is available to a DST trustee, no matter how obviously it might benefit investors.
That's the paradox sitting at the center of the whole structure. Investors hand over every operational decision to the trustee, and the trustee itself is boxed in by IRS rules tighter than almost any other real estate ownership form allows. Nobody in a DST, investor or trustee, has the flexibility that a direct owner takes for granted. The seven restrictions per Rev. 2004-86 as described in EisnerAmper and NexPoint sources).
Tax claims and limitations arising from the passive ownership structure
The tax mechanics follow directly from the grantor trust treatment described above. Because investors are treated as the direct owners of the underlying real estate for tax purposes, they get to claim their share of depreciation and report income and expense on their own returns. That's a real benefit, and it's part of why DSTs work as 1031 replacement property in the first place.
But the same structure that grants that treatment also closes off a different tax benefit. The trust structure that grants that treatment also closes off a different tax benefit. It's a structural impossibility. The practical consequence: DST investors cannot claim real estate professional status against their DST holdings, so they can't use any losses generated by the DST to offset non-passive income the way an actively involved property owner might.
On the deferral side, the numbers add up fast. A 1031 exchange into a DST defers federal long-term capital gains tax (as high as 20%), Section 1250 unrecaptured depreciation recapture (25%), the 3.8% Net Investment Income Tax, and, in most states, state-level capital gains tax too eisneramper.com. For a top-bracket investor in a high-tax state, all of that combined can push the deferred rate past 35% of the total gain eisneramper.com. 2025-32, the 20% long-term capital gains rate applies above $549,900 for single filers and $613,700 for married filing jointly, while the NIIT applies above $200,000 single and $250,000 joint, not indexed for inflation JLL Income Property Trust JLL Income Property Trust. Investors report the deferral itself on Form 8824, filed with the tax return for the year the exchange closes.
None of this changed with the One Big Beautiful Bill Act, signed into law July 4, 2025 JLL Income Property Trust JLL Income Property Trust. The One Big Beautiful Bill Act, signed July 4, 2025, left Section 1031 fully intact, no dollar cap, no income limit, no transaction limit, so the DST-as-1031-replacement-property strategy remains available in full for 2026 JLL Income Property Trust JLL Income Property Trust. What the structure eliminates: because DST trustees hold all operational authority, required by Rev. 2025-32.
How one transaction pathway works
Some DSTs are built with a second act in mind. The path runs in two steps: an investor first completes a standard 1031 exchange into a DST, then, after holding the interest for some period, contributes that interest to a REIT's operating partnership in exchange for operating partnership, or OP, units. That second step, the UPREIT contribution, sits outside the original exchange and can itself trigger a taxable event if it isn't planned carefully with an advisor.
This isn't a niche or experimental maneuver. JLL Income Property Trust has completed 15 full cycle UPREIT transactions totaling $1.2 billion as of May 2025, with the most recent, Diversified II DST, closing May 7, 2025 with $185 million in assets. Since JLL Exchange launched in 2019, the platform has drawn more than $1.85 billion across 26 separate DST offerings JLL Income Property Trust JLL Income Property Trust. Numbers at that scale suggest an institutional path with a track record behind it.
What changes for the investor once they make that move is this. OP units carry different liquidity characteristics than a DST interest, in some structures they can eventually convert into REIT shares, offering a path to liquidity that a DST alone doesn't provide. But that liquidity comes at the cost of a different governance framework. A DST beneficiary is constrained by the seven deadly sins but has a defined fractional claim on a specific asset pool. An OP unit holder instead is subject to the REIT operating partnership agreement, which is a different, and often more complex, governance document. Anyone considering a DST program built around an eventual UPREIT rollup should understand that shift in advance, since the DST is often structured from day one with that eventual merger into the REIT already in mind.
Real DST programs in practice: assets, scale, and how the structure plays out for investors
Two recent JLL Income Property Trust offerings show what these programs actually hold and how quickly institutional capital fills them DST Investment Advisors. JLLX Diversified VII, fully subscribed April 29, 2025, was a $105 million program structured as two Delaware Statutory Trusts, with assets including a 199-unit multifamily residential community in Trumbull, CT and a Class A, 211,000 square foot industrial warehouse facility in Chandler, AZ DST Investment Advisors JLL Income Property Trust. JLLX Diversified VIII, fully subscribed May 28, 2025, was a $158 million program with assets including a 323-unit multifamily residential community in Wilsonville, OR and a grocery-anchored shopping center of approximately 147,000 square feet in Cedar Park, TX JLL Income Property Trust JLL Income Property Trust.
In both cases, every decision about which properties to buy, what lease terms to accept, and how to manage the assets was made by LaSalle Investment Management as investment advisor and JLL Income Property Trust as sponsor, well before any investor money came in the door. Investors weren't choosing between the Trumbull apartment complex and some other option DST Investment Advisors JLL Income Property Trust. They were buying into a program that was already fully assembled.
Both programs illustrate the seven deadly sin on no new capital: once fully subscribed and closed to subscriptions, no additional investor capital can enter the structure. Once the raise hits its target, the door shuts, permanently, for that trust.
The sponsor pointed to multifamily and industrial as sectors with strong underlying fundamentals, and the broader data backs that framing: CBRE reported U.S. multifamily investment volume rose 9.1% in 2025 to $161.6 billion, while industrial leasing activity jumped 12%, the second-highest annual total after 2021 DST Investment Advisors / CBRE. What "institutional-grade" means in concrete terms is access. A 199-unit apartment complex or a 211,000-square-foot warehouse isn't something an individual investor typically buys outright; fractional ownership through a DST is the only practical way in JLL Income Property Trust.
And the lease-modification restriction from Revenue Ruling 2004-86 isn't abstract when you put it against a real asset. If the anchor tenant at the Chandler warehouse wanted to renegotiate its lease terms, the trustee legally could not accommodate that request, unless the tenant had gone insolvent or filed for bankruptcy. A better deal for the trust, sitting right there, off the table by rule.
How to evaluate a DST sponsor's quality
Since investors hold no operational control whatsoever, the entire arrangement rests on the sponsor's competence and its discipline in staying inside the boundaries of Revenue Ruling 2004-86. A trustee that slips up on any of the seven restrictions doesn't just risk a bad quarter. It can make investor income immediately taxable, collapsing the deferral the whole exchange was built to achieve.
That dependence is why due diligence on a sponsor has to go deeper than a glossy asset summary. Track record matters first: how many prior offerings has the sponsor taken full cycle, how many UPREIT conversions has it actually completed, and how many years has it run DST programs. Compliance history matters just as much, has the structure ever drawn an IRS challenge to its like-kind treatment, has the sponsor ever tripped one of the seven restrictions. Fee transparency deserves real scrutiny too, since sponsors collect fees at acquisition, during asset management, and again at disposition, and an investor locked into the trust can't renegotiate any of that after closing. Exit strategy needs to be spelled out as well: is this DST designed to roll into an UPREIT, and if so, on what kind of timeline.
It also helps to be clear-eyed about what SEC involvement does and doesn't mean here. It means the paperwork has been filed. Sponsor quality, property selection, and tax planning done properly ahead of time are what actually protect an investor's return, and if a sponsor underperforms, there's little an investor can do beyond whatever remedy the trust agreement happens to spell out. There's no operational lever to pull, no board seat to claim, no vote to call.
Where the QI fits in a DST exchange
The investor either understood the trade they were making before the money moved, or they didn't. SOURCE PAGES (what the pages behind the outline's links say).