Tenancy in Common Structures for Multigenerational Property Ownership
Each owner can direct their share to different heirs and separately exchange proceeds at sale.
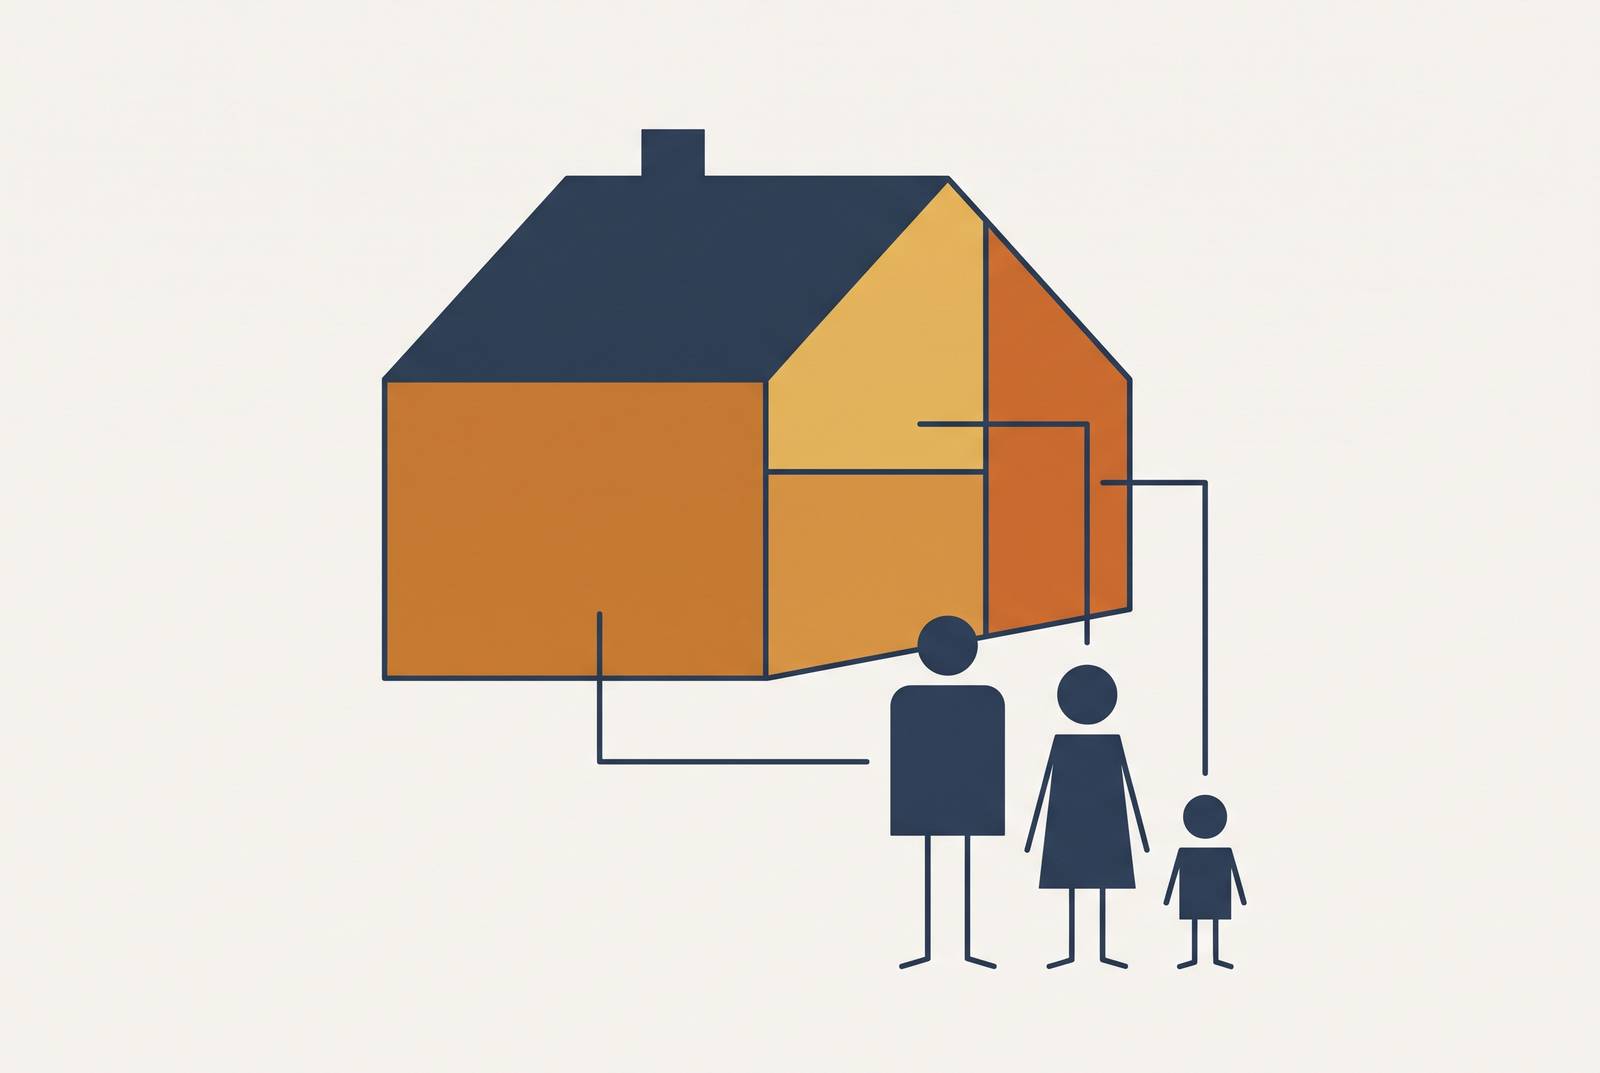
Tenancy in common suits multigenerational property ownership because it separates each owner’s share and inheritance choices without dividing the property itself. That flexibility can reconcile unequal contributions, different borrowing profiles, and competing plans for heirs. Its benefits depend, however, on coordinating the deed, mortgage, co-ownership agreement, estate plans, and any future tax-deferred exchange before the family commits.
Why multigenerational households are turning to TIC now
Home prices have risen dramatically since 2019 while median household income growth has lagged, pushing families to combine resources to qualify for a purchase. Pooling income expands borrowing capacity beyond what either generation might achieve alone. Each contributor needs control over where their investment goes at death, particularly when the household includes children from different relationships or several branches of heirs.
Newlyweds might buy with their parents initially, then move toward independent ownership when they can support the mortgage and property taxes themselves. Families therefore need more than a way to purchase together.
What TIC actually is — and what "undivided interest" means in practice
TIC gives each co-owner a fractional interest in the whole property. Ownership percentages do not divide the living space. A 25% owner has the same right to use and occupy the entire property as a majority owner. Exclusive occupancy arrangements therefore require more than a percentage on the deed.
Shares can be unequal, and owners can acquire them at different times through separate transactions. Each owner can sell, transfer, or borrow against their interest independently, without permission from the other co-owners. In most states, TIC is the default when property passes to two or more unmarried people without a specified tenancy type. An explicit TIC deed states each party’s undivided fractional percentage. The structure can also arise through inheritance or when a joint tenant transfers an interest and severs the joint tenancy.
How TIC differs from joint tenancy and why that difference matters for families with blended or branching heirs
Joint tenancy directs a deceased owner’s share automatically to the surviving co-owners, regardless of the will. TIC instead allows the share to pass to named beneficiaries, or through intestacy without a will. The distinction can determine which family branch inherits. A parent who owns as a joint tenant with a new spouse may leave nothing from that property to children from a prior relationship, because the share passes to the spouse and could later reach the spouse’s children.
TIC also permits unequal shares, while joint tenancy requires equal ownership. That helps align title with different generations’ contributions. The inheritance control comes with a trade-off, however, because an individually held TIC interest generally passes through probate. A life estate offers another route, allowing an elder lifetime occupancy before the property passes automatically to named remaindermen outside probate. But the elder cannot sell without their consent, and shares of sale proceeds are actuarially determined by the elder’s age.
How mortgage qualification works when multiple generations are on the loan
Lenders add up qualifying income and borrowers’ monthly debts to work out the debt-to-income ratio. More income does not automatically improve the application. A parent’s debts may cancel out the help their earnings provide, and lenders usually use the lowest middle credit score among borrowers to set the rate tier and decide who qualifies. Families should model applications with and without a lower-credit co-borrower before applying.
Title and the mortgage are separate documents, so the owners and borrowers need not match perfectly. Income that qualifies can come from W-2 employment, documented self-employment, Social Security, and retirement distributions. ADU rental income may also qualify, depending on the lender and loan type, with requirements including a separate entrance and kitchen and documented rental history or a signed lease. Federal regulators proposed a rule as of March 2026 that would allow income-producing ADUs to be financed under a key government-backed loan program. The comment period closed June 1, 2026, but a proposal is not an established underwriting entitlement.
The TIC agreement — what it must cover to prevent the structure from breaking down
A TIC agreement governs how independent ownership rights function inside a shared household. Without it, state defaults fill the gaps. Owners are generally presumed responsible for mortgage payments, taxes, insurance, maintenance, and repairs in proportion to ownership, although joint-and-several liability can allow creditors to pursue an owner for the full amount. Separately, any owner can seek partition to force a sale of the entire property without a majority vote. This right to force a sale can upset every generation’s plans for where to live.
The agreement should specify ownership percentages, cost allocation, payment defaults, and whether capital improvements change shares. It should also address rights of first refusal, approval of incoming owners, occupancy assignments, common areas, and guest policies. Rules for mediation and buyouts give owners steps to follow when they disagree before going to court. Death and disability provisions should cover heir succession, any required sale by heirs, insurance to fund buyouts, and powers of attorney. For a multigenerational home, an attorney-drafted governance document is essential.
Estate planning considerations specific to TIC — probate exposure, Medicaid recovery, and the caregiving gap
After a Medicaid recipient dies, states can seek reimbursement from the probate estate, which generally includes an individually held TIC share. TIC does not itself protect that asset. Some states extend recovery to assets passing outside probate, so families should not assume that joint tenancy necessarily resolves the exposure.
A different limitation appears when one child provides substantial care for an aging parent. TIC assigns ownership but does not itself reward caregiving or adjust shares as circumstances change. Without an estate plan, intestacy can also bring in heirs whom the surviving owners did not choose or expect. Each owner therefore needs a plan for their interest.
A trust can provide tools that title alone lacks. It can address changed circumstances, compensate a caregiving child, avoid probate, and potentially limit Medicaid recovery exposure, though it requires additional structure and cost. TIC and trust ownership are not mutually exclusive. Layering a trust over one or more TIC shares can preserve fractional ownership while addressing the caregiving and probate gaps.
How TIC enables independent 1031 exchanges when multigenerational owners eventually sell
With TIC, each owner of property held for investment or business use has their own choice about tax deferral. Each owner holds real property directly. Partnership and multi-member LLC interests do not qualify for Section 1031 treatment, so their owners cannot individually exchange those interests without a structural conversion. A qualifying TIC interest can itself serve as relinquished property.
At a sale, one TIC owner can exchange their pro-rata proceeds into replacement property while another chooses different property or cashes out. No entity dissolution is required for those separate decisions. Eligibility still depends on each owner’s use. In a mixed-use arrangement, investment-use owners may qualify while owners occupying the property as their primary residence do not. A qualifying exchange defers federal capital gains tax, depreciation recapture, applicable state tax, and net investment income tax, preserving capital for reinvestment while leaving the liability in place.
The 1031 rules TIC co-owners must follow — timelines, identification, and the "whichever is earlier" deadline trap
The time allowed for an exchange starts when the sale of the relinquished property closes. Replacement property must be identified in writing within 45 days, and that identification period runs within the 180-day total exchange period. The “whichever is earlier” completion rule also means the 180-day figure should not be treated as an unconditional allowance. Establishing the applicable completion deadline with the exchange advisors is therefore part of planning before identification ends.
Under the commonly used 3-property rule, an exchanger may identify up to three properties regardless of their total value. Like-kind treatment is broad for qualifying real estate, allowing a rental single-family property to be exchanged for vacant land, apartments, or commercial property. Primary residences and fix-and-flip inventory do not qualify. Each TIC owner follows an independent timeline, so one owner’s missed identification deadline does not invalidate another’s timely exchange. California, Oregon, Montana, and Massachusetts also have clawback rules that track deferred gains when replacement property is out of state and the exchanger later cashes out.
The IRS conditions TIC arrangements must meet to preserve 1031 eligibility and avoid partnership recharacterization
The IRS can treat a nominal TIC arrangement as a partnership when its operations resemble an active business venture. Simply co-owning rental property, with normal maintenance and leasing, does not by itself create a tax partnership. But partnership recharacterization eliminates the owners’ ability to exchange their individual interests independently, making the conditions addressed in Rev. Proc. 2002-22 a structural concern.
That distinction becomes particularly important when owners attempt a drop-and-swap before selling. A family can dissolve an LLC or partnership and distribute proportional TIC interests, but conversion immediately before a sale creates risk. The IRS can challenge closely timed steps under the step transaction and substance-over-form doctrines. Families considering this approach should allow sufficient time under the TIC structure and document genuine co-ownership activity before pursuing an exchange.
The "swap till you drop" strategy and what inherited TIC interests mean for the next generation
Successive exchanges can extend deferral until an owner dies. At inheritance, a stepped-up basis resets the inherited interest’s basis to fair market value rather than the original purchase price, potentially eliminating accumulated deferred gain. TIC permits this strategy at the individual owner level. Each owner makes their own exchange decisions and estate plan, and each heir gets the basis adjustment on the share they inherit.
Heirs who receive undivided interests can independently hold, sell, or pursue a qualifying exchange. Their preferences may nevertheless conflict over the underlying property. An heir seeking an exit may invoke partition, which makes succession provisions in the co-ownership agreement essential even when the tax plan works as intended. Most exchanges are one-time transactions followed by a taxable sale, so a continuing exchange chain requires sustained planning. The full multigenerational benefit depends on aligning ownership, the agreement, each estate plan, and exchange mechanics from the start.
What to put in place before structuring a multigenerational TIC deal
Before putting in money, families should state ownership percentages clearly in the deed and have the co-ownership agreement drawn up. The agreement should resolve cost allocation, partition risk, rights of first refusal, heir succession, and dispute procedures. Families should model combined income, debt, and credit effects, then determine who belongs on the mortgage separately from who holds title. Each owner should also have an estate plan before deed execution, with a will at minimum and a trust where probate or caregiving goals require it.
For an investment purchase, the next step is to establish whether each owner’s intended use supports eventual exchange treatment. Before a relinquished-property closing, a Qualified Intermediary must be in place, because exchange funds cannot pass through the exchanger’s hands. Selection should favor segregated, federally insured fund holding, a dedicated senior Exchange Officer rather than a commissioned salesperson, publicly published interest rates on held funds, and no unnecessary fees. Any planned entity-to-TIC conversion also needs sufficient holding time and documented co-ownership activity. Formation decisions can be difficult to unwind, so this educational framework should be applied with a real estate attorney, an estate planning attorney, and a tax advisor for exchange questions.