How Boot Exposure and Debt Replacement Rules Shape Which Replacement Property You Can Actually Afford
Proper debt and equity planning prevents taxable boot in 1031 exchanges.
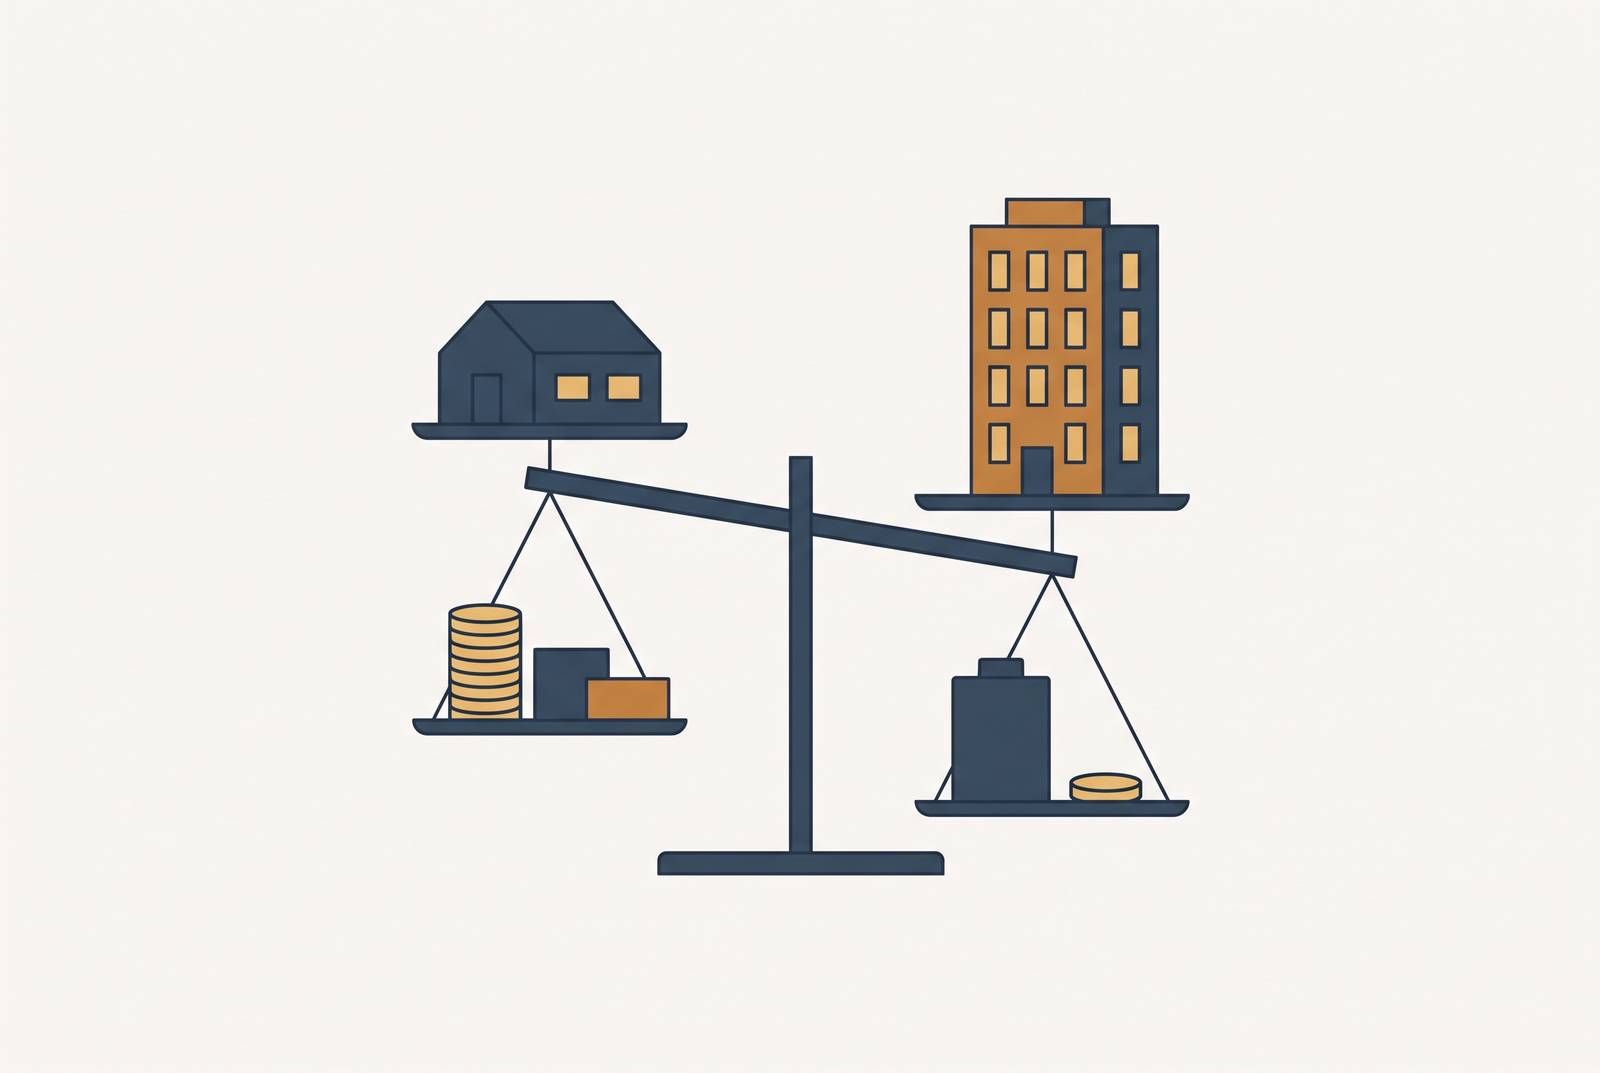
A 1031 exchange can defer gain on investment real estate, but boot exposure and debt replacement rules determine which replacement properties can deliver full deferral. The workable purchase must meet the value requirement, absorb the sale’s net equity, and replace retired debt or cover the debt gap with outside cash. Those requirements belong in the property search.
Why boot and debt rules matter before you start shopping for a replacement property
The standard exchange plan starts with the cash. An investor expects to collect sale proceeds, roll them into another property, and defer the tax. That model accounts for equity but leaves out the mortgage paid off when the relinquished property sells. A replacement can absorb every dollar held by the qualified intermediary and still produce taxable boot if its financing leaves an uncovered debt shortfall.
The mistake starts when an investor picks a property before planning for the tax. By the time an investor discovers the gap at closing, the available choices may no longer include different financing, additional cash, or another replacement. The result can be a partially or fully taxable exchange that the investor expected to complete without an immediate tax bill.
What boot actually is and how it gets created
Boot is value an exchanger receives in a form other than like-kind replacement property and is taxable in the year of the exchange, up to the gain realized. Boot does not, by itself, void the exchange. Instead, it removes the affected portion of gain from deferral while the qualifying portion can remain deferred.
Cash boot is the most visible form. It arises when sale proceeds do not reach the replacement property, whether because the investor buys a cheaper asset, pockets some proceeds, or leaves exchange funds unused with the qualified intermediary. Certain costs paid from exchange funds, including prorated rents, security deposits, and loan origination fees, can also create cash boot. Legitimate selling costs, such as commissions and title fees, lower net proceeds without creating boot.
Mortgage boot is less obvious because no cash needs to change hands. It arises when debt retired on the relinquished property exceeds replacement debt and the investor does not cover the difference with additional cash. The IRS treats relief from a mortgage obligation as value received. The old loan payoff therefore counts in the exchange calculation even though the investor never gets those sale proceeds to spend.
Property boot is a third, narrower category. It includes value received through nonqualifying assets such as personal property or equipment bundled into a transaction. The IRS states that the Tax Cuts and Jobs Act of 2017 limited Section 1031 to real property, excluding personal and intangible property. For replacement-property targeting, however, the debt rule deserves closer attention because it governs both financing and the investor’s required cash contribution.
How the IRS taxes boot and why the ordering of gain makes it expensive
The IRS allocates it first to the more heavily taxed depreciation-related gain before reaching long-term capital gain on appreciation. Net Investment Income Tax can add a surcharge for higher-income investors, and state income tax can add another layer. Some states do not conform to federal 1031 treatment at all.
The ordering makes a modest shortfall potentially expensive. As an investor moves from one exchange to the next, adjusted basis and accumulated depreciation carry over, so the tax owed on depreciation-related gain can grow over time. An investor therefore needs more than the expected capital gains rate to work out the cost of mortgage boot. The final amount depends on income, filing status, and state, which makes the reinvestment test the practical starting point for avoiding an unplanned bill.
The three-part reinvestment test that governs whether a replacement property qualifies for full deferral
Full deferral generally requires three conditions to work together. First, the replacement property must meet the equal-or-greater-value requirement relative to the relinquished property. This establishes the purchase-value floor before the investor considers preferred asset types or locations. A property is not suitable for full deferral merely because its price fits the cash available from the sale.
Second, all net equity from the sale must be reinvested. Even with a higher purchase price, all proceeds must go into the replacement. Third, the investor must replace the debt paid off on the relinquished property, unless additional outside cash covers the debt shortfall.
Meeting the value and debt requirements while retaining exchange equity creates cash boot, while reinvesting all equity without covering retired debt can create mortgage boot. Before identification, the investor therefore needs to know the sale price, the net equity left after legitimate closing costs, and the mortgage balance paid off. Of those figures, retired debt has the most direct effect on which replacements the investor can finance without adding their own money.
Why the debt replacement rule is harder to satisfy than it looks — and the asymmetry that trips experienced investors
The debt rule permits substitution in only one direction. Additional cash can cover a debt shortfall, but additional borrowing cannot offset exchange cash that the investor withdraws. 1031 Capital Advisors expresses the distinction directly. “Cash cures a debt gap; new debt does not cure a cash grab”. Taking on a larger replacement loan therefore does not create permission to take sale proceeds out tax-free.
This asymmetry can frustrate an otherwise sensible investment preference. An investor selling appreciated, leveraged property may want a lower-debt replacement or an all-cash purchase. Yet relief from the old mortgage is effectively “phantom cash”, value received without a corresponding deposit in the investor’s bank account. Unless replacement borrowing or outside cash offsets that relief, reducing leverage produces mortgage boot.
The source of qualifying debt offers some flexibility. Universal Pacific 1031 states that replacement debt can come from a new mortgage, an assumed loan, or other legally enforceable financing tied to the property. Personal borrowing such as credit card debt usually does not qualify.
Timing imposes a separate constraint on that flexibility. Replacement financing must be funded and the acquisition closed within the 180-day deadline. If the lender is late, the investor may have too little debt or may be unable to close on time at all. The constraint is manageable, but only when the debt and equity requirements are mapped before properties are identified.
How to calculate your boot exposure before you identify a replacement property
The practical calculation begins with the relinquished property’s gross sale price. Under the equal-or-greater-value test, that is the initial value benchmark for the replacement search. Next comes net equity after the mortgage payoff and legitimate closing costs, including commissions and title fees. That figure identifies the exchange cash the replacement must absorb.
The third input is the mortgage balance retired at closing. It establishes the replacement borrowing requirement unless the investor plans an outside-cash contribution. Together, the inputs produce a working minimum purchase floor, namely the higher of the relinquished property’s sale price or the sum of net equity and required replacement debt. This is a targeting model rather than a substitute for the transaction’s final tax calculation.
The investor can cover the debt gap with personal funds or cash from a refinance of another property, but cannot count the exchange proceeds again as that contribution. Otherwise, the same equity is being assigned two jobs, reinvestment and debt replacement. Identifying the outside-cash source before the search shows whether the preferred leverage level is actually attainable.
Closing expenses also need to be classified before the investor relies on the available funds. Paying non-exchange expenses from exchange proceeds can create cash boot and leave less money for the replacement purchase. A deliberate partial exchange is different from that accidental leakage. An investor may choose to receive a defined amount of boot, defer the remaining eligible gain, and accept the planned tax cost, provided the choice is structured before closing.
How the debt and equity floor shapes which property types and price points are actually reachable
A lower-priced replacement may fit the investor’s cash budget but fail to meet the requirements for full deferral. The tax bill then changes how much the investor saves. The relevant price band is therefore not simply what the investor can purchase, but what the investor can purchase under the intended exchange structure.
Financing then narrows the surviving choices by market and asset type. An investor paying off a large debt needs a replacement that allows about as much qualifying borrowing, unless outside cash is on hand. Properties offered on an all-cash basis, markets where lenders will not provide the required leverage, and asset classes with substantially different financing terms may fail that screen.
A Delaware Statutory Trust gives the investor another way to plan. Many DST offerings include trust-level non-recourse debt that can help satisfy debt replacement without the investor personally qualifying for or guaranteeing a new loan. That can work for an investor who wants less personal responsibility for borrowing while keeping the exchange debt allocation the rules require. Accredited investors can buy such offerings through private placement, with risks that include illiquidity, fees, and loss of principal.
The three-property rule permits identification of three properties regardless of value, so an unsuitable candidate uses a limited selection. If the 45-day window closes before the investor finds an alternative, a property that fails the debt or equity floor cannot simply be replaced with a newly discovered choice. Applying the filter before identification preserves options that late arithmetic cannot restore.
The exchange structure must be in place before the sale closes. A qualified intermediary must be engaged and the exchange agreement signed before proceeds reach the investor’s hands or bank account, which would trigger receipt and end the exchange. The intermediary holds the proceeds, prevents constructive receipt, and prepares the documentation governing the 45-day identification and 180-day closing windows.
For a high-value commercial exchange, the investor needs a provider that can keep the funds safe and carry out the exchange. The investor should look for segregated, federally insured accounts, a fidelity bond covering employee misconduct, errors and omissions insurance, and a multi-year track record. There is no federal QI license to substitute for that review. Membership in the Federation of Exchange Accommodators is another useful criterion, although the investor remains responsible for vetting the provider.
Account-opening speed, access to a senior dedicated exchange officer, transparent fund handling, and whether interest is returned to the client are practical points of comparison. These features support the movement and administration of exchange equity, but they cannot repair an unsuitable replacement purchase. Before signing the agreement, the investor should already know the sale-price benchmark, how much net equity must go into the purchase, and how much retired debt must be replaced.
Financing and cost planning must proceed on the same timetable. Working with the lender before identification closes lowers the risk of being unable to fund an otherwise suitable property within 180 days. Exchange-eligible closing costs should be distinguished from expenses that require other funds. If partial boot is intentional, its amount and expected tax cost should be documented before closing, ahead of reporting on Form 8824. Affordability is settled before the search begins, when the investor can still choose a property and financing structure that fit the exchange.